Introduction
The credit score to rent an apartment is often the deciding factor in whether you'll get approved, what deposit you'll pay, or if you'll need a co-signer. A credit score is a prediction of your credit behavior—specifically, how likely you are to pay a loan back on time—based on information from your credit reports. Landlords use this number to assess the risk that you'll go 90 days or more without paying rent.
The score itself is a numerical representation of your creditworthiness, calculated using factors like payment history, outstanding balances, and past financial behavior. Companies use credit scores to make decisions on whether to offer you a mortgage, credit card, auto loan, and other credit products, as well as for tenant screening. Most credit scores fall on a 300-850 scale, and the higher your score, the lower the risk you present to a landlord.
What Credit Score to Rent an Apartment Do Landlords Expect?
Rental applications compete. When multiple applicants vie for the same unit, landlords often choose the candidate with the strongest financial profile. Your credit score serves as a quick, standardized measure of reliability. A higher score can mean faster approval, lower deposits, and more negotiating power. A lower score doesn't automatically disqualify you, but it does require you to address concerns upfront and demonstrate stability through other documentation.
Understanding the credit score threshold landlords expect—and the steps you can take if you fall short—puts you in control of the process. If you're working to strengthen your overall financial profile, consider exploring strategies like how to automate your savings without thinking about it to build the reserves that can offset credit concerns. The rest of this guide walks you through the credit benchmarks landlords use, the challenges renters face, and practical solutions to improve your approval odds.
Problem Statement
Renters across the country face a common obstacle when searching for housing: the credit score barrier. Landlords and property management companies routinely use credit scores as a primary screening tool, and many applicants discover too late that their score doesn't meet the threshold. This gatekeeping mechanism can lock out otherwise qualified tenants who have stable income and rental history but carry credit blemishes from past financial setbacks.
Why Credit Scores Create Rental Barriers
A credit score is a numerical representation of a person's creditworthiness based on their credit history. Companies use credit scores for tenant screening, which directly affects your rental application outcome. When your score falls below a landlord's cutoff—often somewhere in the 620–650 range—your application may be rejected outright, regardless of your current financial stability or employment status.
The challenge intensifies because credit scoring models weigh factors that may not reflect your ability to pay rent. Past medical debt, a foreclosure from years ago, or even a collections account you've since resolved can drag down your score and follow you through multiple rental applications. Lower scores may limit your housing options or result in higher security deposits, creating a financial catch-22 for renters trying to rebuild.
The Information Gap
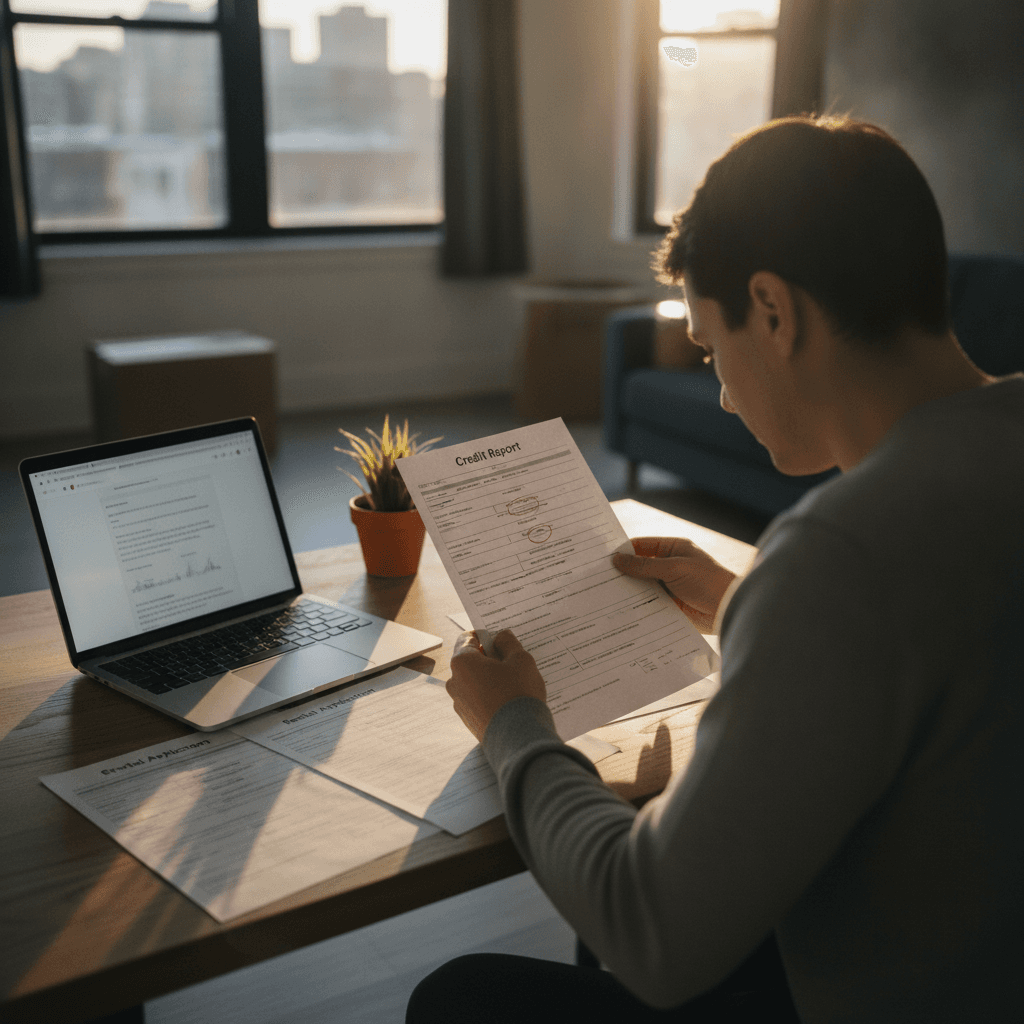
Most renters don't monitor their credit reports regularly and may not discover errors or negative items until they're in the middle of an apartment search. By that point, disputing inaccuracies or addressing issues takes weeks—time you don't have when competing in a tight rental market. Understanding how to dispute credit report errors can prevent last-minute surprises, but many applicants only learn this lesson after a rejection.
The lack of transparency around what constitutes an acceptable credit score for renting compounds the problem. Unlike mortgage lending, where score ranges and underwriting standards are more standardized, rental criteria vary widely by landlord, property type, and local market conditions. This inconsistency leaves renters guessing whether their score will pass muster until they've already invested time and money in the application process.
Solution Steps: Understanding Credit Scores for Renting
Understanding how credit scores work and what landlords look for gives you a clear path to strengthening your rental application. The process breaks down into manageable steps that address both immediate needs and long-term credit health.
Know Where You Stand
Improve Your Credit Profile
Build a Strong Application Package
Once you understand your credit position, gather supporting documents that show financial stability. Pay stubs, bank statements, and reference letters from previous landlords can offset a lower score. If you've recently improved your credit habits, a brief explanation of past issues and current progress can provide helpful context.
For renters concerned about credit score myths and common misunderstandings, knowing the facts helps you approach applications with confidence rather than fear.
Scores are not static—consistent habits over time move the needle in your favor.
Understanding credit scores removes the mystery from the rental process. With a clear picture of where you stand and a plan to strengthen your profile, you can approach landlords prepared and informed.
Tips and Tricks for Renting with a Low Credit Score
A lower credit score doesn't mean you're locked out of the rental market. Many renters successfully secure apartments by taking proactive steps that demonstrate reliability beyond the three-digit number. The key is understanding what landlords actually care about and addressing those concerns directly.
Build a Stronger Application Package
When your credit score falls below what most landlords prefer, compensate with documentation that tells a fuller story. Gather recent pay stubs, bank statements showing consistent deposits, and letters from previous landlords confirming on-time rent payments. This evidence shifts the conversation from what went wrong in the past to what you're doing right now.
Consider offering a larger security deposit or prepaying several months of rent if you have the cash reserves. While not every state allows higher deposits, where permitted, this approach reduces the landlord's financial risk and can tip the scales in your favor when competing against applicants with stronger credit profiles.
Target the Right Properties and Landlords
Not all rental markets weigh credit scores equally. Individual landlords managing one or two properties often have more flexibility than large property management companies bound by corporate underwriting policies. Smaller buildings, private rentals, and neighborhoods with higher vacancy rates typically offer more room for negotiation.
When apartment hunting, be upfront about your credit situation early in the process. Explain any negative marks with context — a medical bill in collections or a period of unemployment tells a different story than chronic missed payments. Transparency builds trust and saves everyone time.
Improve Your Credit While You Search
Even small improvements can make a difference during your apartment search. Review your credit report for errors — inaccuracies are surprisingly common, and disputing them can boost your score within weeks. If you find mistakes, learn how to dispute credit report errors to clean up your file before landlords pull it.
Pay down existing balances where possible, especially on credit cards. Your credit utilization ratio — how much credit you're using versus your total available credit — affects your score quickly. Bringing a maxed-out card below 30 percent utilization can produce visible score changes in one billing cycle.
Avoid applying for new credit while apartment hunting. Each application typically triggers a hard inquiry, which can temporarily lower your score. Since landlords will also pull your credit, minimize additional hits until after you've signed a lease. Understanding hard vs soft credit inquiries helps you protect your score during the search.
Leverage Alternative Rental Arrangements
If traditional leases remain out of reach, explore month-to-month rentals, sublets, or roommate situations where the primary leaseholder has already passed the credit check. These arrangements often require less stringent screening and give you time to rebuild credit while maintaining stable housing.
Some newer rental platforms and services report rent payments to credit bureaus, turning your monthly housing cost into a credit-building tool. Once you're in a place, consistent on-time rent payments can gradually strengthen your profile for future moves.
Conclusion
Understanding what credit score to rent an apartment gives you a clear target and a roadmap for improvement. While many landlords prefer scores above 620, the reality is that rental approval depends on more than a single number—your income, rental history, and willingness to address concerns all play critical roles in the decision.
If your credit score falls short of typical thresholds, you're not locked out of the rental market. Offering a larger security deposit, providing a co-signer, or demonstrating stable income can offset lower scores and show landlords you're a reliable tenant. Proactive steps like disputing errors on your credit report and paying down high balances can also improve your score faster than you might expect.
The rental application process rewards preparation. Know your credit standing before you apply, gather documentation that highlights your strengths, and be ready to explain any credit challenges honestly. Landlords appreciate transparency and a clear plan for financial stability. For more strategies on building financial resilience, explore How Much Emergency Fund Do You Need? Saving & Storage Guide.
Take control of your credit today—whether that means checking your report for errors, setting up automatic payments, or simply understanding where you stand. The apartment you want is within reach when you approach the process with knowledge and a plan.
Related reading
Can You Buy a House Without Credit? Buying a House Without Credit